
Hit by a Car While Biking in Las Vegas: Whose Insurance Pays?
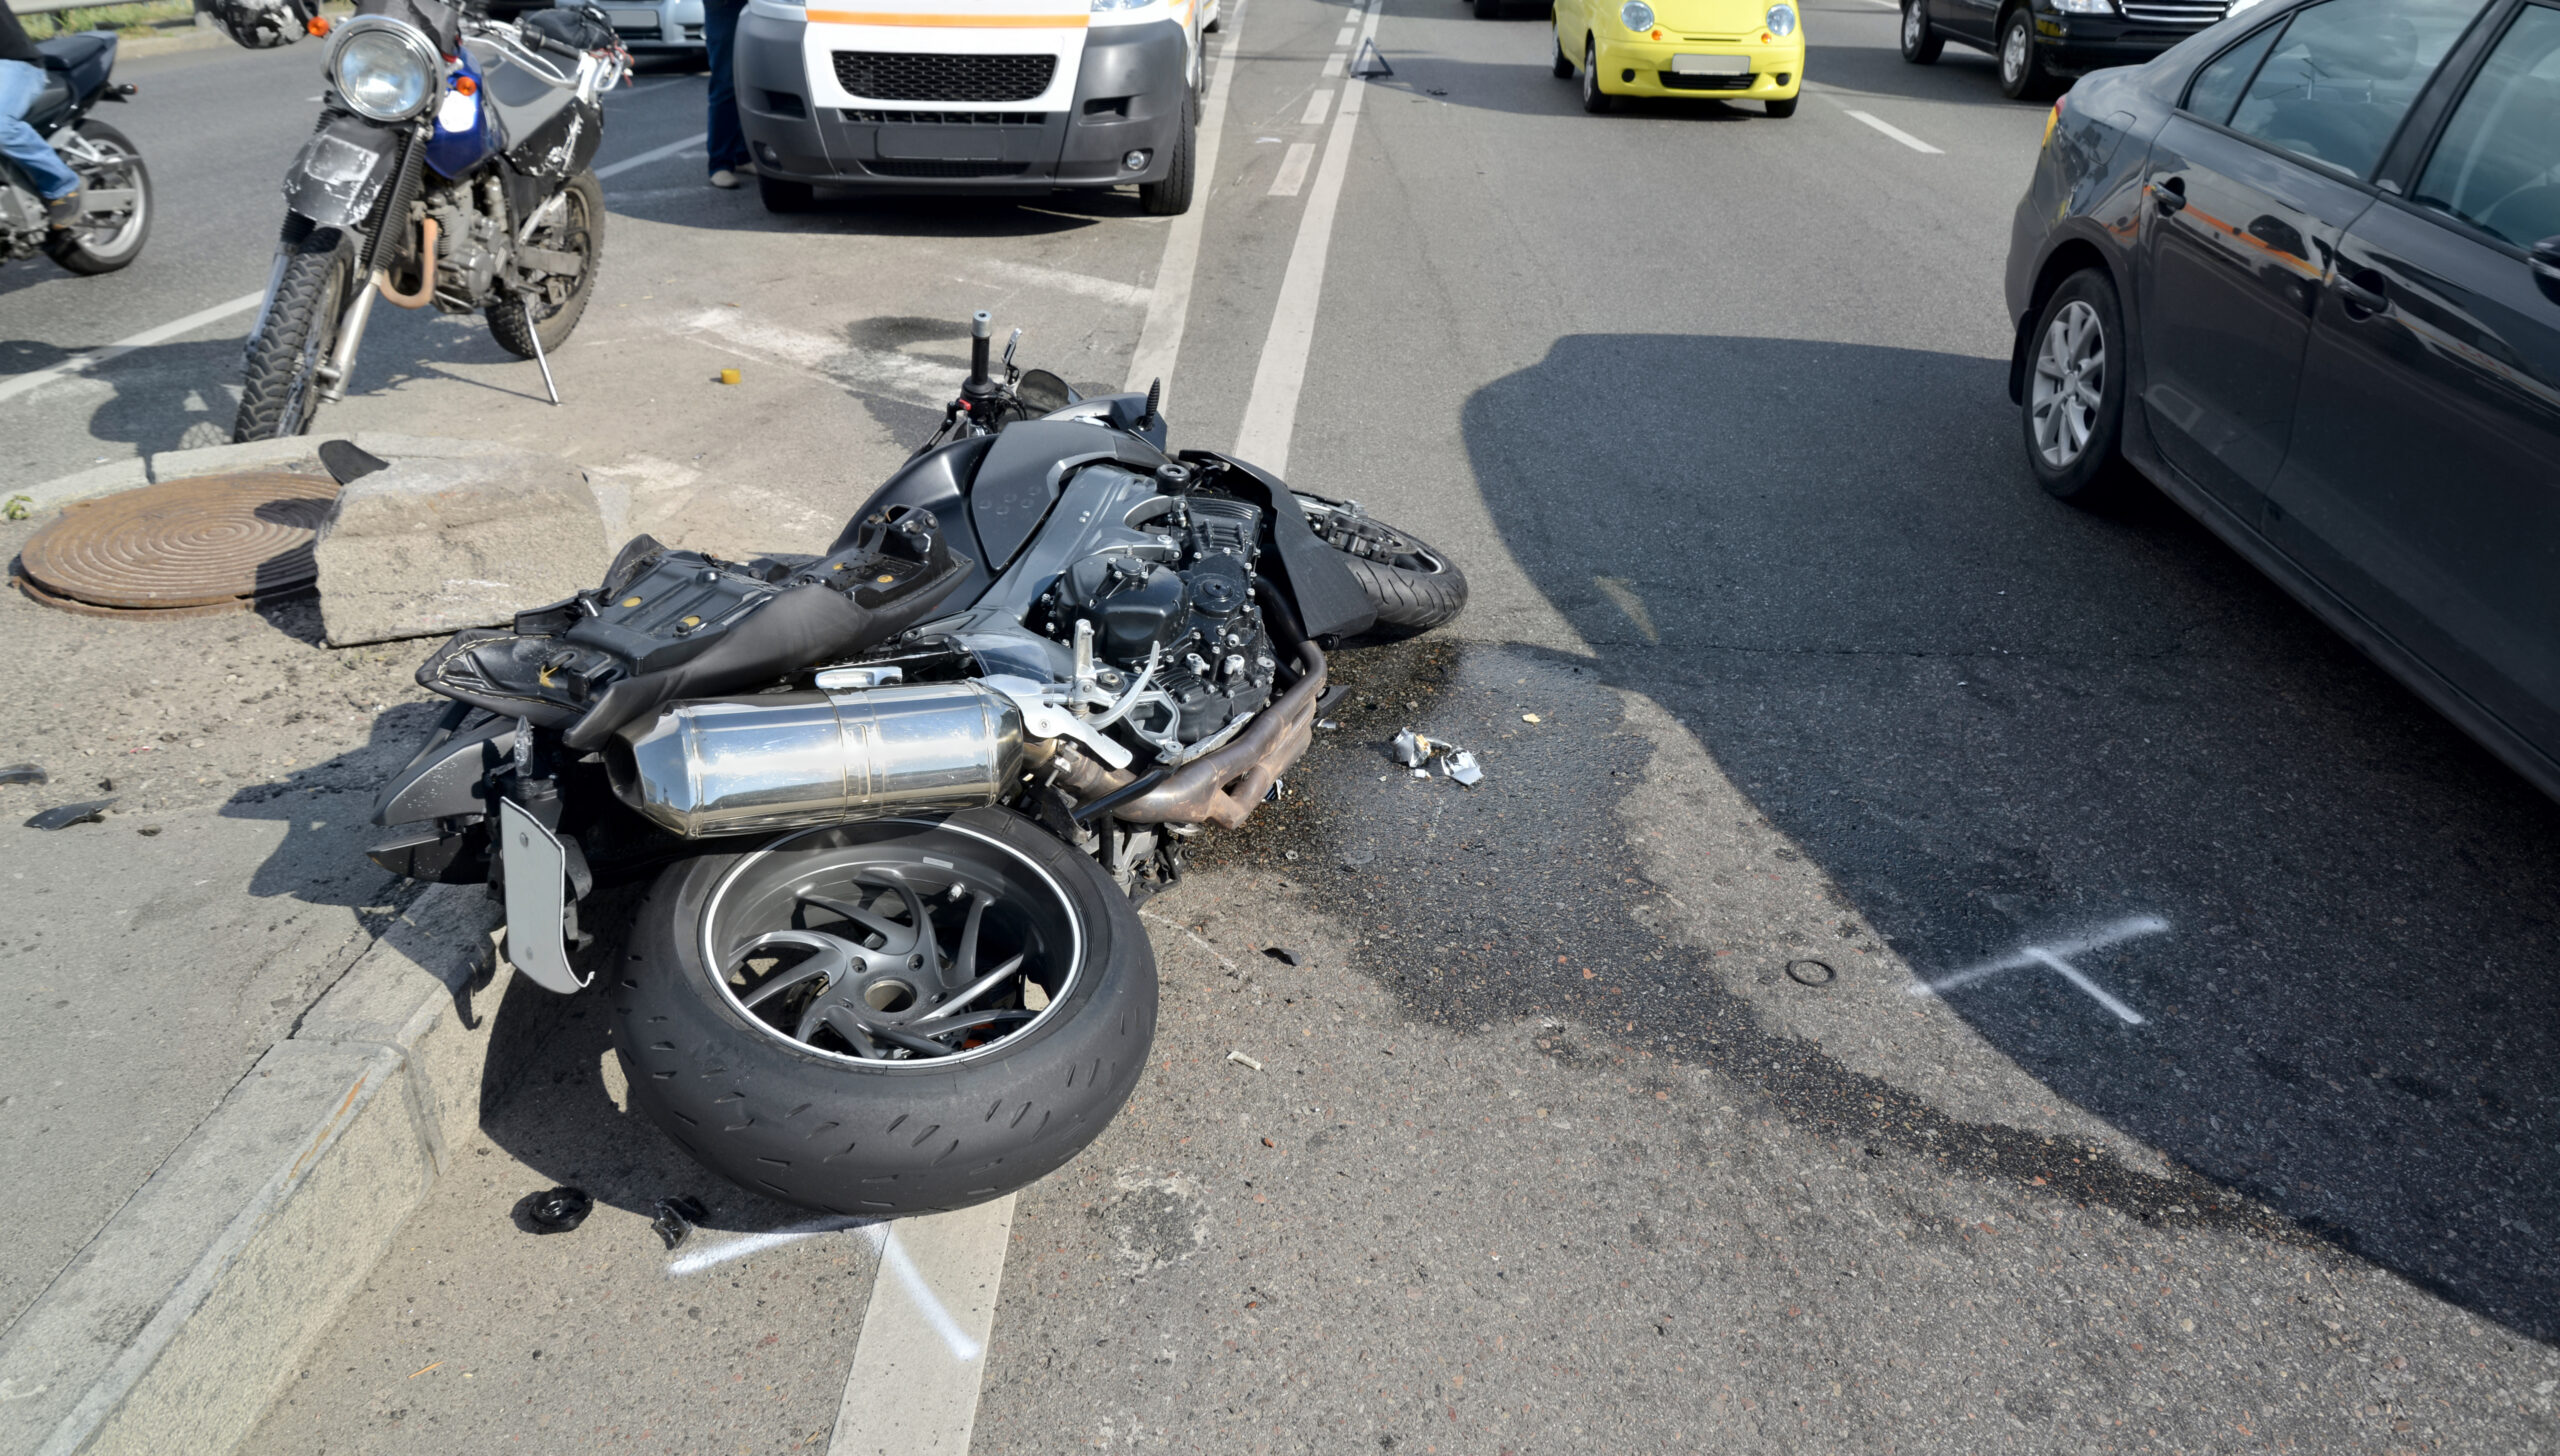
You were on your bike, doing everything right, and a driver still hit you. Now you are staring down medical bills, a wrecked bicycle, and time off work, and one question keeps surfacing, “whose insurance is supposed to pay for all of this?” You weren’t in a car, so it feels like the usual rules don’t apply.
They do, and the answer is often more favorable than injured cyclists expect. Between the driver’s coverage and, in many cases, your own auto policy, there may be more than one source of compensation available to you. Knowing where to look is the difference between absorbing these costs yourself and being made whole.
Start here: Nevada is an at-fault state
Nevada follows an at-fault system, which means the driver who caused the crash, and their auto insurance, is responsible for your injuries. When a car hits a cyclist, the driver’s bodily injury liability coverage is the first place your claim goes.
The catch is how little that coverage is required to be. Nevada’s minimum liability limits are just 25/50/20: $25,000 for injuries to one person, $50,000 per accident, and $20,000 for property damage. A single ambulance ride, ER visit, and follow-up care can blow past $25,000 quickly, and a serious bike-versus-car injury often does. Worse, roughly one in eight Nevada drivers carries no insurance at all.
That is exactly why the driver’s policy is often only the beginning of the story.
Your own auto insurance may cover you, even on a bike
Here is what surprises most people: if you own a car, your own auto policy may pay for a crash that happened while you were riding a bicycle.
The coverage that makes this possible is uninsured/underinsured motorist (UM/UIM) coverage. Unlike liability insurance, which is tied to a specific vehicle, UM/UIM generally follows you as a person. That means it can apply even when you were not in your car, including when you were struck while riding a bicycle, depending on your policy language.
UM/UIM steps in when the at-fault driver:
- Has no insurance at all, or
- Has too little insurance to cover your full injuries (that is the “underinsured” part), or
- Fled the scene in a hit-and-run.
A few Nevada-specific points worth knowing:
- It’s optional, but you were required to be offered it. Nevada does not force drivers to buy UM/UIM, but insurers must offer it, and any decision to reject it has to be made in writing. Many people carry this coverage without realizing it — and some who think they rejected it may not have a valid written waiver on file.
- Check your declarations page. Your policy’s declarations page lists whether you have UM/UIM and at what limits. If you are not sure, that is the first document to pull.
- Medical payments coverage may help too. If your policy includes “MedPay,” it can cover medical bills regardless of who was at fault, and it also typically follows you as a person.
What if the driver had no insurance or fled the scene?
Hit-and-run crashes are common, and they are frightening precisely because it feels like there is no one to hold responsible. But if a vehicle physically struck you and then fled, your uninsured motorist coverage is designed for exactly this situation and may pay for your injuries as though the driver had been insured.
These claims do come with specific proof and notice requirements, so reporting the crash promptly to police and to your own insurer matters. An attorney can help make sure a hit-and-run claim is documented the way your policy requires.
Other places compensation can come from
Depending on your circumstances, additional sources may include:
- Your health insurance, which can cover medical treatment now (though it may later seek reimbursement out of your settlement, a process called subrogation).
- A household member’s auto policy. If you live with a relative who carries UM/UIM coverage, you may be covered as a resident relative under their policy — even if you don’t own a car yourself.
Untangling which policies apply, and in what order, is one of the most valuable things an attorney does early in a bicycle case.
Why this gets complicated fast
It would be nice if filing these claims were simple. It usually isn’t.
A UM/UIM claim is made against your own insurance company, and even your own insurer has a financial interest in paying you as little as possible. Adjusters may undervalue the claim, dispute your injuries, or argue you were partly at fault. That last point matters in Nevada, where comparative negligence reduces your recovery by your share of fault, and bars it entirely if you are found more than 50% responsible. Insurers know this, and they often try to shift blame onto the cyclist.
Having someone who can identify every available policy, push back on lowball offers, and protect you from tactics designed to reduce your payout is how injured cyclists actually recover what they are owed.
Talk to a Las Vegas bicycle accident lawyer today
If a driver hit you while you were biking in Las Vegas, you may have more coverage available than you realize — and you should not have to figure it out alone while you heal. At Jerez Law, we track down every source of compensation, from the driver’s policy to your own, and fight to get you the full amount you deserve, in English or Spanish, with no fees unless we win.
Contact us for a free, confidential consultation. We are available 24/7, and there is no cost and no pressure to find out which policies may cover your crash.
Frequently Asked Questions
Whose insurance pays if a car hits me while I’m biking in Las Vegas? Because Nevada is an at-fault state, the driver who hit you is responsible, and their auto liability insurance is the first source of payment. If that driver was uninsured, underinsured, or fled the scene, your own uninsured/underinsured motorist (UM/UIM) coverage may also pay for your injuries.
Can I use my own car insurance if I was on a bicycle and not driving? Often, yes. UM/UIM and medical payments coverage generally follow you as a person rather than your vehicle, so they can apply even when you were struck while riding a bike — depending on your specific policy language.
What if the driver who hit me had no insurance or left the scene? Your uninsured motorist coverage is built for exactly these situations. If an uninsured or hit-and-run driver physically struck you, that coverage may pay for your injuries, though hit-and-run claims carry specific reporting and proof requirements.
Does Nevada require uninsured motorist coverage? No. UM/UIM coverage is optional in Nevada, but insurers are required to offer it, and any rejection must be made in writing. Many people carry it without realizing, so it is worth checking your policy’s declarations page.
What are Nevada’s minimum car insurance limits? Nevada requires at least 25/50/20 in liability coverage: $25,000 for bodily injury per person, $50,000 per accident, and $20,000 for property damage. These minimums are often too low to cover a serious bicycle injury.
How long do I have to file a claim after a Las Vegas bicycle accident? Nevada generally gives you two years from the date of the crash to file a personal injury claim (NRS 11.190). Acting sooner is better, because evidence and witness memories fade quickly.